By The Cakani Law Firm, P.C.
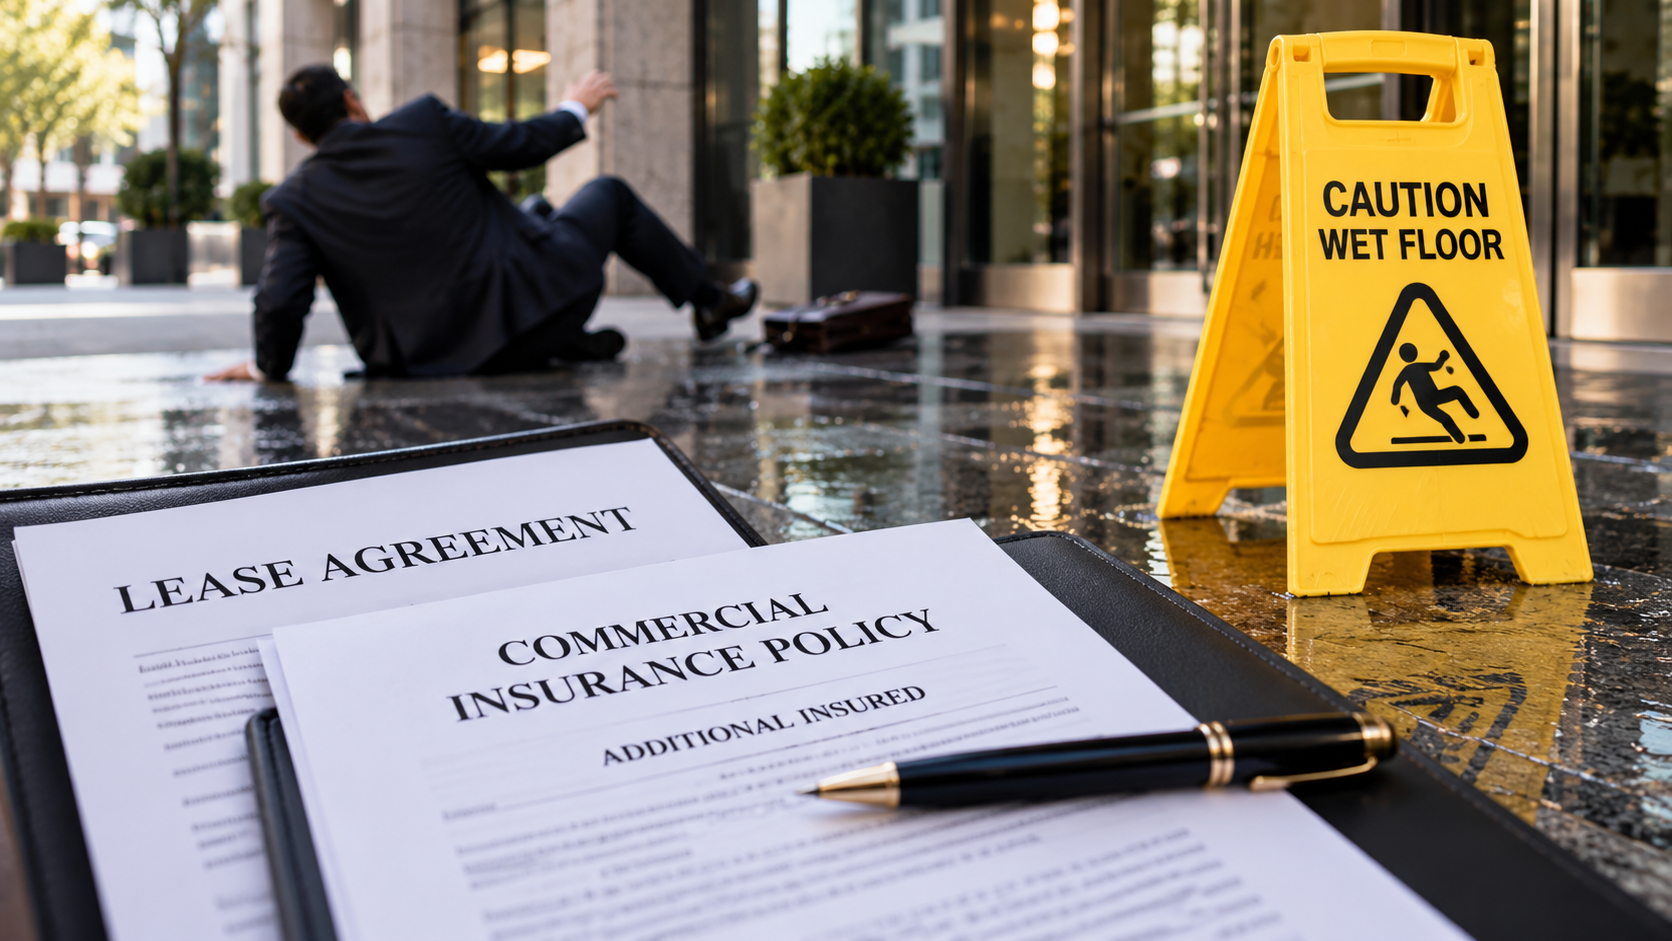
Picture this: you bought a commercial building outright. No mortgage, no lender requiring insurance, and you never got around to buying a liability policy. Then someone slips and falls on the property — and you’re named in a personal injury lawsuit.
For most commercial property owners, that is the nightmare scenario: a building worth millions of dollars exposed to a lawsuit with no insurance company standing behind you.
That is exactly the situation one of our clients faced. Here is how we turned it around — and what every commercial property owner in New York should take from it.
The Hidden Insurance in Your Lease
Our client didn’t have a policy. But their tenant did.
The lease required the tenant to carry commercial general liability insurance and to name the landlord as an additional insured. That is a common lease provision — and many owners forget it exists until they need it.
An additional insured is someone who is not the policyholder but who is still protected by the policy for certain claims. When a lease requires it, the landlord can ask the tenant’s insurance company to defend them in a lawsuit and to cover the liability.
Our client asked. The insurance company said no.
Why Insurers Deny Additional Insured Claims
A first denial is common, and it is not always the final word. Insurers often reject these requests because:
- The request (called a “tender”) was vague and didn’t point to the specific policy language that gives coverage.
- The insurer claims the accident falls outside the scope of the additional insured endorsement.
- The landlord relied only on a certificate of insurance. In New York, a certificate by itself generally does not create coverage — the actual policy and endorsement control.
- The insurer argues it was not notified in time.
Some of these defenses have merit. Many do not hold up once someone reads the documents carefully.
What We Did
When the owner called The Cakani Law Firm, P.C., we moved on two fronts at once.
First, we protected the client in the lawsuit. We answered the complaint so the owner was not at risk of a default, and we filed a third-party complaint against the tenant, holding it to its obligations under the lease.
Second, we went after the coverage. We read the lease and the insurance policy line by line. Then we re-tendered the claim — this time citing the policy’s own additional insured provision, supported by the lease and the certificate of insurance, and making clear that we were prepared to litigate the coverage question in court if necessary.
The Result
The insurance company reversed its position.
The tenant’s $1,000,000 policy is now covering our client’s legal defense and liability in the case — with defense counsel paid by the insurer, not by the property owner.
A Note About Our Practice
The Cakani Law Firm, P.C. focuses on representing plaintiffs — people who have been injured and need someone in their corner. That is the heart of our practice.
In special circumstances, such as helping a former client, we also take on defense matters. Years of litigating injury claims from the plaintiff’s side have given us a deep, practical knowledge of how these cases are defended and how insurance coverage really works — additional insured endorsements, tenders of defense, coverage denials, and how insurers decide when to pay. That knowledge is what made the difference for this client.
Lessons for Commercial Property Owners
- Read your leases. Look for insurance-procurement and additional insured clauses. Your lease may be worth far more than you think.
- Get the policy, not just the certificate. Ask tenants for a copy of the additional insured endorsement every year when they renew.
- Act fast after an incident. Notify the tenant and its insurer in writing as soon as you learn of an accident or a claim. Delay gives the insurer an argument to deny.
- Make a specific tender. Point the insurer to the exact policy language, the lease clause, and the facts of the claim.
- Don’t stop at the first “no.” A denial can often be challenged — and the threat of a court fight over coverage can change an insurer’s answer.
- Consider your own policy. A tenant’s insurance is a backstop, not a replacement. Owners should carry their own liability coverage.
Has an Insurer Denied Your Coverage?
If you own commercial property and have been sued — or if an insurance company has refused to defend you — talk to us before you decide what to do next. The answer may already be in your lease.
The Cakani Law Firm, P.C.
200 Mamaroneck Ave, Suite 505
White Plains, NY
Call: (212) 962-0500
We also speak Spanish and Albanian. Call us today for a consultation.
Attorney Advertising. Prior results do not guarantee a similar outcome. This article is for general information only and is not legal advice. Reading it does not create an attorney-client relationship.